JPMorgan's new DIFC branch: is your private banking deposit protected by the UAE's guarantee scheme?
A global bank opening inside the DIFC is regulated by the DFSA, not the Central Bank, and that distinction decides whether your deposit sits inside the UAE's deposit guarantee scheme or outside it.
The question clients actually ask
When a name like JPMorgan opens a private banking branch inside the DIFC, the first question from a prospective client is rarely about service levels. It is: if something goes wrong, is my money protected the way it would be at a conventional UAE bank? The honest answer is no, not in the same way, and understanding why matters before you move seven or eight figures into a DIFC account.
Two separate regulators, two separate regimes
Onshore UAE banks (National Bank of Fujairah, Emirates NBD, ADCB and the like) are licensed and supervised by the Central Bank of the UAE under the federal banking law. The Central Bank operates a deposit guarantee scheme that protects eligible deposits held with its licensed member banks up to a prescribed threshold if a member bank fails.
A DIFC branch of an international bank is a different animal entirely. It is licensed by the Dubai Financial Services Authority (DFSA) under the DIFC's own regulatory framework, operating under the DFSA Rulebook rather than the Central Bank's prudential regime. The DIFC is a common law financial free zone with its own courts, its own companies regime, and its own financial regulator. Crucially, the Central Bank's deposit guarantee scheme is built around its own licensed members. A DFSA-regulated DIFC branch is not a member, and deposits placed with it do not automatically fall within that scheme's protection.
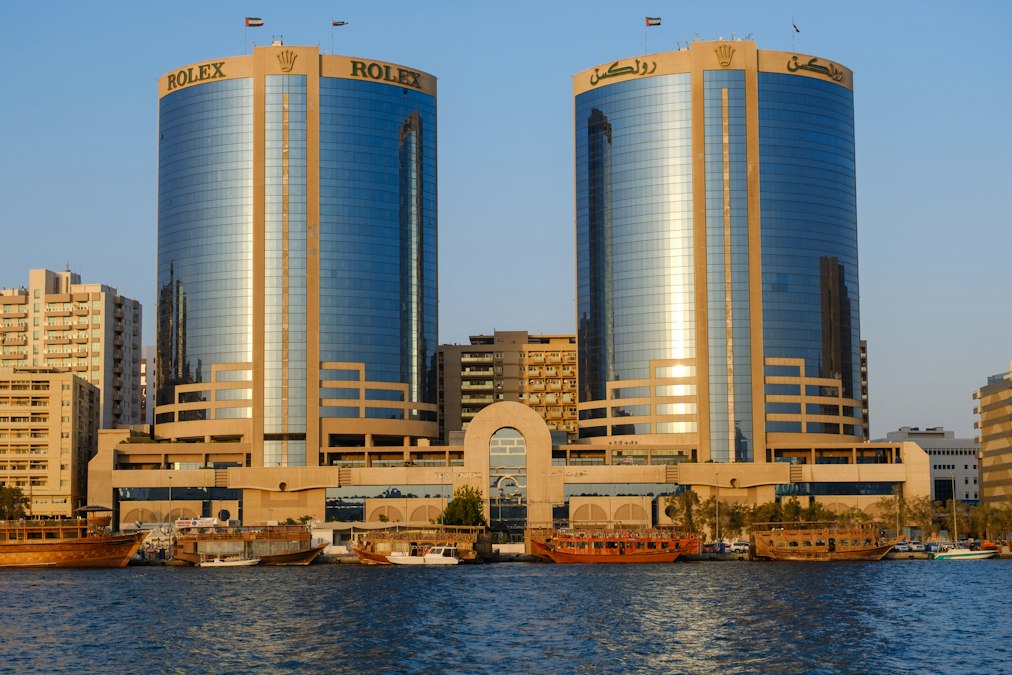
The glass tower may say JPMorgan, but the deposit sitting inside it answers to a different safety net to the one protecting your AED current account down the road.
What actually protects your money in a DIFC private bank
This does not mean a DIFC account is unprotected, it means the protection comes from a different source:
- Prudential supervision: the DFSA applies its own capital adequacy, liquidity and risk management requirements to licensed banking firms, broadly modelled on Basel standards, with ongoing supervisory oversight comparable in rigour to onshore regulation.
- Client asset and money rules: where a DIFC firm holds client money rather than taking it on balance sheet as a deposit (relevant for custody, investment and advisory mandates sitting alongside the private bank relationship), the DFSA's client asset rules require segregation from the firm's own assets, which is a different and in some ways stronger protection than a deposit guarantee, though it operates on a different legal basis.
- Group strength: for a global systemically important bank, the practical credit risk on a deposit is usually assessed against the group's own balance sheet and regulatory capital position in its home jurisdiction, not against a DIFC-specific backstop.
- No automatic compensation scheme: unlike UK or EU depositor protection schemes, there is currently no DIFC-specific deposit compensation fund equivalent to the Central Bank's onshore guarantee. If a DIFC bank failed, recovery would run through ordinary insolvency and DIFC court processes rather than a pre-funded guarantee payout.
What this means practically for a prospective client
Before opening or expanding a private banking relationship in the DIFC, a GC or family office principal should ask the bank directly:
- Is the product a deposit booked on the DIFC branch's balance sheet, or a custody/investment holding subject to client asset segregation rules?
- Which entity is the legal counterparty: the DIFC branch, or a booking centre in another jurisdiction (London, New York, Singapore) with its own protections?
- Does the relationship documentation specify DIFC Courts jurisdiction, and does that affect enforcement timelines against the group if things go wrong?
None of this should deter sophisticated clients from using DIFC private banking, the DFSA's supervisory standard is robust and the centre has attracted exactly this calibre of institution for good reason. But the deposit guarantee comfort that applies onshore does not travel across the DIFC's gates automatically, and documentation should be reviewed on that basis rather than assumed.
Key instruments: DIFC Regulatory Law; DFSA Rulebook (including Prudential and Client Asset provisions); Federal Decree-Law No. 14 of 2018 concerning the Central Bank and the organisation of financial institutions and activities (as amended). General information, not legal advice.